Risky Places to Use Your Debit Card (and What to Use Instead)

Your debit card is convenient, easy to use, and connected directly to your checking account. But that convenience can also mean direct access to your money is on the line if something goes wrong. Unlike credit cards, debit cards pull funds directly from your bank account. If fraud occurs, the money may disappear immediately and can take time to recover while the financial institution investigates.

That’s why it’s important to know where using a debit card may put you at greater risk and when a different payment method might be a safer option. Below are some of the most common places where debit card fraud can occur and what you can do to protect yourself.

Gas Station Pumps

Paying at the pump is one of the most common places criminals target. Gas pumps can be vulnerable to card skimming devices, which secretly capture card information when you insert or swipe your card. These devices can be difficult to detect and may transmit your data to thieves instantly.

Safer options:

  • Use a credit card (or cash), instead of a debit card when at a gas station.
  • When traveling outside of NJ, pay inside instead of directly at the pump.

Outdoor ATMs

ATMs located outside convenience stores, gas stations, or other high-traffic areas can present a risk. As these ATMs may be less monitored, criminals sometimes attach skimming devices or hidden cameras to capture card numbers and PINs here too.

Safer options:

  • Use ATMs directly inside a financial institution or in well-lit locations.
  • Shield your PIN when entering it.
  • Regularly monitor your account for any suspicious activity.

Online Shopping

This method of shopping is convenient, but entering your debit card information online can expose your bank account if the retailer experiences a breach or if the site is fraudulent. With debit cards, fraudulent transactions may immediately withdraw the funds from your account – even while the investigation is underway.

Safer options:

  • Use a credit card for online purchases.
  • Shop only on secure websites (look for “https” at the beginning of the URL).
  • Consider using digital wallets (PayPal, Apple Pay, Google Pay, etc.) or virtual card numbers when available.

Bars, Restaurants, and Busy Retail Environments

Any situation where your card leaves your sight, even briefly – can increase the risk of unauthorized use. In busy environments like bars or restaurants, it can be easier for card information to be copied or mishandled.

Safer options:

  • Use a credit card.
  • Use contactless or mobile payments when available.
  • Review your receipts and account transactions regularly.

Why Credit Cards Often Offer More Protection

Both debit and credit cards have fraud protections, but they work differently. If fraud occurs on a credit card, the funds are not tied to your checking account – and you can dispute transactions without immediately losing funds. With debit cards, the money comes directly from your bank account and may take time to be restored. This is why many financial experts recommend using credit cards for certain transactions – especially online purchases, travel, and higher-risk environments.

Smart Habits to Protect Your Cards

No matter where you use your card (or which kind of card), a few simple habits can help protect your finances:

  • Set up transaction alerts.
  • Review your account regularly for unfamiliar charges.
  • Report lost cards or suspicious activity immediately.
  • Use contactless payments or digital wallets when possible.

Learn More: When to Use Credit vs. Debit

Both debit and credit cards have a place within your financial toolkit. Understanding when to use each can help you protect your money and manage your spending more effectively.

Learn more in our guide: Credit vs. Debit: Which Should You Use?
Protect Your Kids’ Devices from Scammers: A Parent’s Guide to Online Safety

Phones, tablets, gaming systems, and laptops are part of everyday life for today’s kids. These devices are used for schoolwork, entertainment, and staying connected with friends and family. However, with increased access comes increased risk. Online scammers have been known to target young users through fake apps, phishing messages, gaming platforms, and social media.

At First Financial, we believe protecting your finances also includes protecting your family’s digital life. Here are practical steps parents, guardians, and caregivers can take to help keep children safe online and reduce the risk of scams.

1. Turn On Automatic Updates

Software updates often fix security vulnerabilities that scammers and hackers exploit. If devices aren’t updated regularly, they may be exposed to preventable threats. Make sure automatic updates are enabled for:

  • Operating systems (phones, tablets, computers)
  • Apps and games
  • Web browsers
  • Security software

Setting updates to install automatically ensures devices stay protected without relying on yourself or your kids to have to remember to click “update.”

2. Use Strong, Unique Passwords

Weak or reused passwords are one of the most common ways scammers gain access to accounts. Teaching kids how to create strong passwords is a critical life skill. Strong passwords should:

  • Be at least 12 characters long.
  • Include a mix of upper and lowercase letters, numbers, and symbols.
  • Avoid personal details like birthdays, school names, or pet names.
  • Be different for each account.

For older children and teens, consider using a password manager to generate and store secure passwords safely.

3. Secure Your Home’s Wi-Fi Network

Your home’s Wi-Fi network connects every device in your household. If not properly secured, outsiders may be able to access it and intercept sensitive information. To strengthen your home’s network:

  • Change the default router name and password.
  • Use strong encryption settings (WPA2 or WPA3).
  • Create a strong, unique Wi-Fi password.
  • Disable remote management features if not needed.
  • Set-up a separate guest network for visitors.

Taking these steps reduces the risk of unauthorized access to your family’s devices.

4. Set Up Parental Controls

Parental controls are valuable tools for managing screen time, blocking inappropriate content, and preventing unauthorized purchases. Most devices and operating systems include built-in parental control features. These tools can help you:

  • Limit access to certain websites or apps.
  • Require approval for app downloads.
  • Set screen time limits.
  • Restrict in-app purchases.
  • Monitor activity where appropriate.

The goal here isn’t surveillance, it’s setting boundaries and building safe digital habits.

5. Teach Good Online Habits

Technology tools are important, but conversations are just as critical. Open communication helps children recognize risks and make smart decisions online. Teach kids to:

  • Be cautious about clicking on unfamiliar links.
  • Ignore messages asking for personal information.
  • Avoid sharing passwords, addresses, or financial details.
  • Be skeptical of “too good to be true” offers.
  • Tell a trusted adult if something feels suspicious.

Encourage your kids to pause before responding to messages that create urgency or fear, which are common tactics used by scammers.

6. Review App Permissions

Many apps request access to cameras, microphones, contacts, or location data. Not all of these permissions are necessary. Before installing apps:

  • Review what permissions various apps request.
  • Disable unnecessary access to location or contacts.
  • Download apps only from official app stores.
  • Periodically review and remove unused apps.

Reducing app permissions helps limit how much personal information is shared.

7. Monitor Financial Activity

Even children’s gaming accounts and app stores can be tied to family payment methods. Regularly review your account statements and transaction history to catch unauthorized charges early. Consider:

  • Setting spending limits.
  • Requiring approval for purchases.
  • Using alerts for account activity.
  • Monitoring bank and credit card statements closely.

Catching suspicious transactions quickly can help prevent larger financial losses down the road.

Protecting What Matters Most

Online safety isn’t a one-time setup. Scammers are constantly evolving their tactics, especially on platforms that are popular with kids and teens. Protecting your child’s devices requires ongoing attention. By combining strong technical protections with honest conversations and proactive monitoring, you can significantly reduce your family’s exposure to online threats.

First Financial is committed to helping families stay informed and protected, both digitally and financially. If you ever have concerns about suspicious activity or fraud affecting your accounts with us, our team is here to help. Contact us today to learn more about safeguarding your financial information and keeping your family safe from scams. Be sure to also subscribe to our First Scoop blog to get the latest in scams and important alerts delivered right to your inbox.

How to Save Money on Maternity Items

Welcoming a baby is an exciting, and often expensive, life milestone. One area that can quietly add up is maternity clothing. Because changes take place quickly and pieces may be worn for only a short period of time, it can feel difficult to justify spending money on a temporary wardrobe. The good news? With a few thoughtful strategies – you can stay comfortable, confident, and financially mindful throughout your pregnancy.

Here are a few ways to save money on maternity clothes and other pregnancy essentials.

1. Start With What You Already Own

Before purchasing new maternity items, take inventory of your current wardrobe. Many non-maternity pieces can work beautifully during pregnancy – flowy tops, oversized sweaters, stretchy leggings, maxi dresses, and open cardigans. You may be surprised at how long you can make your existing wardrobe work with just a little creativity. Stretchy fabrics and layered looks can carry you through multiple trimesters without requiring a full wardrobe overhaul.

2. Wait Before Buying Everything at Once

It can be tempting to shop right away, but your body will continue to change over several months. Instead of buying a large maternity wardrobe early on, consider waiting until you truly need specific pieces. This helps you avoid purchasing items that may not fit comfortably later and keeps you focused on essentials rather than impulse buys. Buying gradually allows you to better assess what you actually wear and need.

3. Explore Secondhand Options

One of the most effective ways to save is through gently used maternity clothes. Consider:

  • Local thrift or consignment stores
  • Online resale platforms
  • Neighborhood and community social media groups

Maternity clothes are often lightly worn, making secondhand options both affordable and practical. Many parents are often happy to pass along items they no longer need.

4. Say Yes to Hand-Me-Downs

Hand-me-downs aren’t just for baby clothes. Friends, family members, or coworkers who have recently been pregnant may still have maternity clothing stored away. Accepting these items can significantly reduce your expenses and you can always pay it forward when you’re finished with them. Some communities even create informal swaps among expecting parents.

5. Shop Sales and Clearance Strategically

If you do purchase new maternity clothes, timing matters. Look for:

  • Seasonal clearance sections
  • End-of-season sales
  • Outlet pricing
  • Promotional discounts

Focus on versatile basics such as one or two comfortable pairs of maternity leggings, a few tops, and a neutral dress that can be mixed and matched into multiple outfits. A small “capsule wardrobe” often works better than buying many single-use pieces.

6. Use Simple Tools to Extend What You Have

Small accessories can make a big difference. Waistband extenders, belly bands, and layering pieces can help your pre-pregnancy pants and tops last longer. These inexpensive items may allow you to delay purchasing maternity-specific clothing altogether.

7. Keep the Big Picture in Mind

Maternity clothing is temporary. While it’s important to feel comfortable during pregnancy, it’s equally important to prioritize long-term financial goals as you prepare for your growing family. Being intentional with maternity purchases frees up room in your budget for future needs – such as baby essentials, childcare planning, and building savings.

First Financial is Here to Help

Preparing for a new baby brings joy, along with new financial considerations. Saving on maternity items is one way to stay mindful of your budget as you prepare for this next chapter. At First Financial, we’re proud to support families during every life stage. Whether you’re looking to strengthen your savings, build an emergency fund, or create a financial plan for your growing household – our team is here to help you make confident, informed financial decisions.

Explore our savings options, budgeting tools, and resources or connect with a team member today to start planning for your family’s financial future. We’re happy to help!

*A First Financial membership is available to anyone who lives, works, worships, volunteers or attends school in Monmouth or Ocean Counties. A $5 deposit in a base savings account is required for credit union membership prior to opening any other account/loan. Contact the Credit Union for more information.

Budget Check Up: Tax Time Is the Right Time

Every year, about 140 million households file their federal tax returns. For many, the process involves digging through shoe boxes or manila folders full of receipts; gathering mortgage, retirement, and investment account statements; and relying on computer software to take advantage of every tax break the code permits.1

It seems a shame not to make the most of all that effort.

Tax preparation may be the only time of year when many households gather all their financial information in one place. That makes it a perfect time to take a critical look at how much money is coming in and where it’s all going. In other words, this is a great time to give the household budget a checkup.

Six Step Process

A thorough budget checkup involves six steps.

  1. Creating Some Categories. Start by dividing expenses into useful categories. Some possibilities: home, auto, food, household, debt, clothes, pets, entertainment, and charity. Don’t forget savings and investments. It may also be helpful to create subcategories. Housing, for example, can be divided into mortgage, taxes, insurance, utilities, and maintenance.
  2. Following the Money. Go through all the receipts and statements gathered to prepare your taxes and get a better understanding of where the money went last year. Track everything. Be as specific as possible, and don’t forget to account for the cost of any lattes on the way to the office each day.
  3. Projecting Expenses Forward. Knowing how much was spent per budget category can provide a useful template for projecting future expenses. Go through each category. Are expenses likely to rise in the coming year? If so, by how much? The results of this projection will form the basis of a budget for the coming year.
  4. Determining Expected Income. Add together all sources of income. Make sure to use net income.
  5. Doing the Math. It’s time for the moment of truth. Subtract projected expenses from expected income. If expenses exceed income, it may be necessary to consider changes. Prioritize categories and look to reduce those with the lowest importance until the budget is balanced.
  6. Sticking to It. If it’s not in the budget, don’t spend it. If it’s an emergency, make adjustments elsewhere.

Tax time can provide you with an excellent opportunity. You have a chance to give your household budget a thorough checkup. In taking control of your money, you may find you are able to devote more of it to the pursuit of your financial goals.

Need some help with preparing your future financial plan? Contact First Financial’s Investment & Retirement Center by calling 732.312.1534. You can also email  maureen.mcgreevy@lpl.com.

Securities and advisory services are offered through LPL Financial (LPL), a registered investment advisor and broker/dealer (member FINRA/SIPC). Insurance products are offered through LPL or its licensed affiliates. First Financial Federal Credit Union (FFFCU) and First Financial Investment & Retirement Center are not registered as a broker/dealer or investment advisor. Registered representatives of LPL offer products and services using First Financial Investment & Retirement Center, and may also be employees of FFFCU. These products and services are being offered through LPL or its affiliates, which are separate entities from and not affiliates of FFFCU or First Financial Investment & Retirement Center.

Securities and insurance offered through LPL or its affiliates are:

  1. IRS.gov, 2025

The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

How Small Businesses Can Use Valentine’s Day to Boost Engagement

Valentine’s Day is a powerful seasonal opportunity for small businesses to connect with customers, build emotional loyalty, and boost engagement. When approached strategically, the holiday can help businesses stand out, attract new customers, and strengthen relationships that last well beyond February 14th. Here are a few smart ways small businesses can use Valentine’s Day to create meaningful engagement and drive results.

Think Beyond Romantic Love

Valentine’s Day has evolved. Today’s consumers celebrate many forms of love, such as friendships, family, coworkers, pets, and even self-love. Expanding your messaging beyond romantic partners allows your business to appeal to a wider audience and feel more inclusive.

Consider promoting:

  • Galentine’s Day gifts or experiences.
  • Self-care services or “treat yourself” offerings.
  • Gifts for family members or pets.

When customers see your business as part of their meaningful moments, engagement naturally increases.

Create Limited Time Offers

Seasonal promotions give customers a reason to take action. Valentine’s Day is a great time to introduce themed bundles, special pricing, or limited time packages that feel timely and thoughtful.

Ideas may include:

  • Pairing complementary products or services.
  • Offering Valentine’s Day gift bundles.
  • Creating a short-term promotion that encourages early purchases or that lasts throughout this year’s long holiday weekend.

These offers add urgency and keep your business top of mind during a busy shopping period.

Use Social Media to Spark Conversation

Valentine’s Day generates strong activity on social media, making it a great time to engage your audience. Interactive content encourages participation and helps extend your reach organically.

Try these out:

  • Asking customers to share who or what they love.
  • Hosting a simple giveaway or themed contest.
  • Running polls or questions related to Valentine’s plans.

These campaigns help build community while increasing visibility for your brand.

Partner with Other Local Businesses

Collaborating with other local businesses can amplify your Valentine’s impact. Cross-promotions or shared packages introduce your brand to new audiences, while also strengthening relationships within your community.

Examples can include:

  • Joint promotions with complementary businesses.
  • Co-hosted events or giveaways.
  • Shared marketing efforts across social channels or via joint emails.

Local partnerships can make the experience more valuable for customers and reinforce your role in the community.

Personalize Your Messaging

Valentine’s Day is rooted in connection, making it the perfect time to personalize your communication. Thoughtful messages will show customers that you value them beyond the transaction.

This could include:

  • A Valentine’s Day email with a personalized offer.
  • Special recognition for loyal customers.
  • Tailored recommendations based on past purchases or services.

Personal touches help customers feel seen and appreciated, in turn increasing engagement and trust.

Start Early and Stay Consistent

Valentine’s Day marketing works best when it starts early. Many customers plan ahead, especially when it comes to gifts, experiences, or reservations. Beginning your outreach in late January or early February allows you to stay visible and relevant throughout the decision-making process. Multiple touchpoints leading up to the holiday help reinforce your message and keep your business top of mind. If you missed the opportunity this year, save these ideas for next year or another upcoming holiday your business may be able to benefit from in 2026.

Turning Seasonal Moments into Long-Term Growth

Valentine’s Day gives small businesses the opportunity to lean into creativity and emotional connection. When done well, it’s not just about a single day or weekend of sales, it’s about building relationships that support long-term success.

At First Financial, we’re proud to support small businesses as they grow and adapt. Our Business Checking Accounts are designed to help Monmouth and Ocean County business owners manage their cash flow, streamline operations, and prepare for seasonal opportunities. With the right financial tools in place, you can focus more on engaging your customers and building a business you love.

Ready to get started? Visit your local branch, call 732.312.1500, or check out our website to find out how you can become a business member today.*

*A First Financial membership is available to anyone who lives, works, worships, volunteers or attends school in Monmouth or Ocean Counties. A $5 deposit in a base savings account is required for credit union membership prior to opening any other account. Other terms & conditions may apply, see credit union for details.

90 Years Strong: Why Banking Local Still Matters

In a financial world that’s increasingly digital, fast-moving, and impersonal, one thing has never gone out of style: people helping people.

That simple idea is what sparked the creation of credit unions nearly a century ago, and it’s the same principle that continues to guide First Financial as we prepare to celebrate 90 years of service today on February 6th!

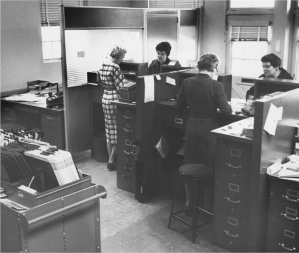
Pictured above: Tellers and members from our first branch location in Asbury Park, NJ when we were Monmouth County Teachers FCU.

Where Credit Unions Began

Credit unions were born out of necessity. In the early 20th century, many working families and small business owners were shut out of traditional banking. Loans were hard to access, savings options were limited, and financial support often depended on who you knew, not what you needed. Credit unions changed that.

Built by communities, for communities – credit unions were designed to be member-owned, not profit driven. Their mission was clear – to provide fair, affordable financial services and help people build stability, security, and opportunity. That mission still matters today.

The Power of People First Banking

While technology has transformed the way we bank, the value of local, relationship-based financial institutions has only grown stronger.

At First Financial, “putting people first” isn’t just a phrase or a tagline, it’s how business gets done every day. When you become a member, that means you’ll receive:

  • Personal service from people who know your name, your financial goals, and your community.
  • Thoughtful lending decisions made locally, not by algorithms or distant headquarters.
  • Financial guidance rooted in trust, not just transactions.

When you walk into our credit union or connect with us online, you’re not just an account number: You’re a member. An owner. A neighbor.

Investing Where It Matters Most

Local banking keeps dollars circulating close to home. Credit unions are known to reinvest in the communities they serve – supporting local businesses, non-profits, schools, and families. Every loan, every account, and every financial decision contributes to a stronger local economy.

Over the past 90 years, First Financial has grown alongside the people and communities it serves, adapting to changing needs while staying rooted in the same cooperative values that sparked its founding.

Trust Built Over Generations

For nine decades, members have turned to First Financial during life’s biggest moments – buying a home, starting a business, planning their future, and navigating unexpected challenges. Those relationships span generations, creating a legacy of stability and care that larger institutions typically can’t replicate. In an era when financial choices can feel overwhelming, having a trusted local partner makes all the difference.

Honoring the Past, Building the Future

As we celebrate our official 90th anniversary, we’re taking time to reflect on where we’ve been and where we’re going.

This milestone isn’t just about longevity. It’s about resilience, adaptability, and staying true to the values that matter most. Throughout the year ahead, we’ll be celebrating this anniversary with member stories, special promotions, and moments that honor our history while looking toward the future. You can find out all the ways we’ll be celebrating 90 years on our website, which will continuously be updated throughout 2026.

Why Banking Local Still Matters

Ninety years strong is more than a milestone, it’s a reminder that when financial institutions are built on trust, service, and community – everyone benefits. Local decisions create lasting impact, and when people come together with a shared purpose – they can build something that lasts for generations.

Thank you for being part of our story. Here’s to 90 years, and many more to come!

Want to learn more about our journey? Explore our history and the people-first values that have guided us for 90 years.

Not a First Financial member yet but want to join us? First Financial membership is open to anyone who lives, works, worships, volunteers, or attends school in Monmouth or Ocean Counties in New Jersey. Learn more about getting started on our website, or stop into any of our branch locations.

*A First Financial membership is available to anyone who lives, works, worships, volunteers or attends school in Monmouth or Ocean Counties.  A $5 deposit in a base savings account is required for credit union membership prior to opening any other account. All personal memberships are part of the Rewards First program and a $5 per month non-participation fee is charged to the base savings account for memberships not meeting the minimum requirements of the program. Click here to view full Rewards First program details. Some restrictions apply, contact the Credit Union for more information.