Sneaky Six: IRS Scams Taxpayers Should Watch Out For

IRS scammers have been around for a long time and they’re sticking around because, unfortunately – people keep falling for their changing tactics. Knowing this, the Internal Revenue Service (IRS) annually publishes a list of tax scams coined the Dirty Dozen, in an effort to increase awareness. Here are some of the most common scams that taxpayers should watch out for year-round, but especially during tax time.

1. Someone Using Your Social Security Number to File Taxes

A scammer might attempt to beat you to the chase – that is, beat you to claiming your own tax refund. This tax scam occurs when a fraudster uses your social security number to file and claim a tax refund. Oftentimes, the first inkling that you’re a victim is if the IRS rejects your tax return once you file. There are various reasons your tax return can be rejected, but it’s a surefire sign of identity theft if the IRS has another tax return filed in your name or a record of income from an employer you don’t work for.

There are resources available to you if someone has stolen your identity and filed a tax return with the IRS. First, you should report the identity theft to IdentityTheft.gov. This government website will aid you in creating various documents, such as an IRS Identity Theft Affidavit and personal recovery plan. You should then submit your Identity Theft Affidavit to the IRS – which notifies them of your case to begin investigating it. Alternatively, you can obtain the Identity Theft Affidavit directly from the IRS and submit it by mail. Lastly, follow the steps in your personal recovery plan to help mitigate the fallout and limit the personal and monetary damages of identity theft.

2. Ghost Tax Preparers that Disappear with Your Cash

While many tax preparers act with professionalism and integrity, tax season gives rise to unscrupulous tax preparers called “ghost preparers” who misguide taxpayers in an effort to make a quick buck or disappear with their refunds. These preparers take advantage of tax credits or deductions the taxpayer doesn’t qualify for, or invent fake sources of income to entice them with fake large refunds. They falsify tax returns in an effort to maximize the amount of the refund because they often charge a “percentage fee” based on the amount of the return. The ghost preparer typically refuses to sign the return after it is prepared, allowing them to disappear with their payment and leave you to deal with the consequences of falsifying a tax return. It is best practice to avoid any tax preparer who charges a cash only fee, does not give you a receipt, or who charges a percentage of your refund as their preparer fee. In addition, one who tries to invent false income or get tax credits and deductions you aren’t qualified for, or who deposits your refund into their own account – will typically “ghost” you.

3. Email and Text Scams

Many scams impersonating legitimate organizations begin with unsolicited emails and text messages, and IRS scams are no exception. The IRS will never demand immediate payment of a tax bill and threaten consequences for not doing so via email or text message. Similarly, the IRS will never notify you of a large tax refund via email or text message. These emails and text messages may also prompt you to click links that would download malicious software on your device or steal your personal and financial information. In the event the IRS needs to contact you, communication is typically initiated through regular U.S. mail. There are exceptions to this, as well as other ways the IRS may contact you – which can be found on the IRS webpage how to know it’s the IRS.

4. Bad Social Media Advice

In an effort to increase views and generate income, some social media influencers have been known to share bad tax advice using clickbait – or content that is designed to attract attention and entice users to click. It is hard to ignore content with headlines such as “find out how this little-known tax deduction can increase your tax refund.” Additionally, some influencers will have you pay to subscribe to gain access their exclusive “tax advice” on various platforms, but they are essentially just taking your money and sending you on your merry way – with incorrect tax advice. If you interact with this content and follow their bad advice, not only will you file a fraudulent tax return – but you also encourage these influencers to continue producing misleading content.

5. Fake Tax Bill

If you receive an urgent request to pay a tax bill with gift cards, cryptocurrency, or any other unusual yet specific method of payment – it’s a fake tax bill scam. The IRS will never call to demand immediate payment or make threats if you cannot render payment. As mentioned previously, the IRS will only contact you via regular U.S. mail.

6. IRS Individual Online Account Help Scam

An individual online account through the IRS provides taxpayers with a portal to access their tax information, such as payment history and tax records. Scammers are now posing as third parties to assist with setting up these online accounts to steal taxpayers’ personal information, submit fraudulent tax returns, and take their tax refunds. The scammer may also sell the personal and financial information to other fraudsters who may file fake tax returns and steal refunds, open loans and credit accounts in the taxpayer’s name, and ultimately steal their identity.  The IRS has a guide to establishing an IRS online account and avoiding scams.

First Financial knows that tax season can be hard enough, and that’s without the worry of being scammed being added into the mix. If you have any questions or reason to suspect that your information has fallen into the hands of a scammer this tax season, don’t hesitate to contact us at 732.312.1500 or visit us at your local branch.
Jet-Set on a Budget: Money-Saving Travel Tips

Let’s face it—this cold weather has all of us dreaming of warmer days, perhaps somewhere near the equator or across the world. Although your winter escape might be just a few clicks away, it’s definitely an expense you might not be able to swing right now. It might be hard to avoid certain travel expenses entirely—think airfare, lodging, or meals, but there are still several ways to save on travel. Whether you’re planning your next long weekend getaway or the once in a lifetime trip of your dreams, consider using these money-saving tips to travel more and spend less.

Be Flexible with Travel Dates, Times, and Even Layovers

Rumor has it that Tuesdays were generally the best day of the week to book flights, historically saving travelers a pretty penny on airfare. While this long-believed advice doesn’t necessarily hold up in every scenario, there are various ways to save money on airfare if your schedule allows for it.

  • Travel Dates: The price of airfare can change drastically from day to day. If the dates of your trip are flexible, see how leaving one or two days before or returning home one or two days after your “target dates” affects the price.
  • Travel Times: The early bird gets the worm, or in this case – cheaper flight options. You probably don’t want to fly in the wee hours of the morning, but cheaper flights are typically at less appealing times. Try looking at late night flights if you’re willing to stay up past your bedtime, too.
  • Layovers: Direct flights offer the added benefit of getting to your destination as quickly as possible, and that benefit doesn’t come free of charge. Many passengers are willing to pay extra money to spend less time in the air and in the airport, typically making flights with layovers comparatively cheaper.

Consider Using a Smaller Airport or in a Neighboring City

Whether it’s your departing or arriving home flight, consider flying to or from a smaller airport or an airport in a neighboring city to increase your options. Airports with more traffic increase airline demand and airfare prices along with them. Airport demand can change due to different factors, such as peak travel seasons and regional or cultural events. For example, flying right into Miami International Airport will be more expensive during college spring break season than the weeks leading up to or weeks immediately following it. It might be less expensive to fly into a smaller airport in the area, and use an additional mode of transportation to get directly to your destination.

Don’t forget to consider the cost of the additional transportation if you choose to fly to or from an airport in a neighboring city. Consider the following situation: You are taking a trip to New York City and debating flying into JFK or Newark airports. The flight to and from Newark airport may be cheaper round trip, but you will have to take additional transportation to get into New York City. This is something to keep in mind when comparing travel costs.

Hotels Aren’t the Only Answer

Consider alternatives to well-known hotel chains, such as AirBnB or VRBO. These accommodations are more unconventional, as you would likely be booking an apartment or house instead of a traditional hotel room. This could even encourage you to cook your own meals and save more money on food during your trip.

… But if a Hotel is the Only Option: Join the loyalty program of the hotel you plan to stay at to save on this trip, or the next. Some hotel chains offer discounted room rates to members of their loyalty program, and many are free to join. If they do not offer discounted room rates your first go-around, they might offer you discounted rates down the line as you accumulate points or as a special offer to members of the program.

What’s in Your Wallet?

Don’t forget the power of your credit card – some credit cards offer added benefits for traveling (like the First Financial Visa Signature Cash Plus Card*), such as additional cash back or points if you book the purchase using your credit card, or discounts on partner chains or resorts.

Additionally, if you have a AAA membership for your vehicle – consider using AAA when booking your trip. Having this membership gives you access to AAA Travel Services from vacation planning with their travel agents, to passport services and discounts on cruises, tours, and vacations.

Savor the Savings on Meals

Depending on where your travels take you – food might be the largest travel expense. Although an unavoidable one, there are various ways to limit just how much this expense has to cost.

  • Lunch is the New Dinner: When comparing lunch to dinner, lunch is almost always the cheaper option. Additionally, Happy Hour is typically the time between lunch and dinner. Even if you’re not looking for a cocktail, certain food items are typically discounted during Happy Hour. Take advantage of this timing to save when you dine out. You can also bring any leftovers back to your lodging and make a dinner out of it, too.
  • Restaurant Tourist Traps: Avoid restaurants that have overly translated menus, menus with more pictures than words, and ones with few dishes native to the area. Additionally, steer clear of eateries that are near main attractions. These establishments are looking for tourists who might not know of a more authentic or affordable option, or who are looking for convenience.
  • Eat Outside of Your Hotel: Unless your hotel offers free breakfast, it is typically cheaper to eat outside of your hotel. The prices of menu items at hotels are usually more expensive than the same items at a local eatery.

Here at First Financial, we hope you can use some of these tips to take that much needed and well-deserved trip. A budget-friendly vacation is possible if you plan ahead and spend wisely. For more personalized assistance and tailored solutions call 732.312.1500, visit a branch, or explore our services online.

*APR varies up to 18% for purchases, when you open your account based on your credit worthiness. The APR is 18% APR for balance transfers and cash advances. APRs will vary with the market based on the Prime Rate. Subject to credit approval. Rates quoted assume excellent borrower credit history. Your actual APR may vary based on your state of residence, approved loan amount, applicable discounts and your credit history. No Annual Fee. Other fees that apply: Cash advance fee of $10 or 3% of the total cash advance amount—whichever is greater (no maximum), Balance transfer fee of $10 or 3% of the balance—whichever is greater (no maximum), Late Payment Fee of $29, $10 Card Replacement Fee, and Returned Payment Fee of $29. A First Financial membership is required to obtain a Visa® Credit Card and is available to anyone who lives, works, worships, or attends school in Monmouth or Ocean Counties. Your First Financial Visa® Cash Plus Credit Card will earn cash back based on your eligible purchase transactions. The cash back will be applied to your current credit card balance on a quarterly basis and be shown cumulatively on your billing statement. Unless you are participating in a limited time promotional offer, you will earn 1% cash back based upon eligible purchases each quarter.

Protect Yourself From Check Fraud Scams

Despite the rise of digital banking, check fraud remains a prevalent financial scam. Scammers use sophisticated techniques to steal and manipulate checks, often leaving victims unaware until it’s too late. Understanding how check fraud works and how to recognize suspicious activity can help protect your finances.

What is Check Fraud?

Check fraud occurs when criminals manipulate, forge, or steal checks to illegally access funds.

Common Types of Check Fraud

  • Check Washing: Thieves steal legitimate checks — often from mailboxes, and modify key details, such as the recipient’s name or the payment amount, before cashing or selling them.
  • Check Kiting: Using multiple accounts to write and deposit bad checks, temporarily covering insufficient funds before withdrawing cash.
  • Forgery: Criminals create counterfeit checks or forge signatures to access funds fraudulently.
  • Fake Checks: Scammers trick victims into depositing fraudulent checks, often under the guise of prize winnings, job opportunities, or overpayment schemes. Once the check is cashed, the fraudster requests the money be sent back, leaving the victim responsible when the check bounces.

How to Recognize Check Fraud

Recognizing fraudulent checks early can help you avoid financial loss. Be on the lookout for these red flags:

  • Unexpected Checks: If you receive a check from an unknown source, verify its legitimacy before depositing it.
  • Spelling and Formatting Errors: Poor grammar, misspelled words, or inconsistent fonts can indicate a counterfeit check.
  • Unusual Check Amounts: If the check amount exceeds what was agreed upon, it may be a scam.
  • Discrepancies in Mailing Address: If the check was mailed from a different location than the issuing bank, proceed with caution.
  • Request for Money Transfers: Be wary if someone asks you to deposit a check and send a portion of the money back. This is a common scam tactic.
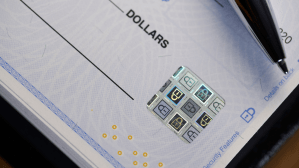
  • Lack of Security Features: Legitimate checks include watermarks and security threading. If these features appear altered or missing, the check may be fraudulent.

How to Prevent Check Fraud

While fraudsters are persistent, there are steps you can take to reduce your risk:

  • Use Secure Payment Methods: Opt for electronic payments, online bill pay, or peer-to-peer payment apps (Zelle, Venmo, etc.) instead of checks when possible.
  • Write Checks with a Fraud-Resistant Pen: Gel pens with permanent ink can make it harder for criminals to alter check details.
  • Check Your Mail Frequently: Avoid leaving checks in your mailbox where they can be stolen and deposit them directly inside a bank or electronically right away.
    • If you deposit electronically, keep the check in a secure place and shred it once it clears.
  • Enroll in Informed Delivery: The U.S. Postal Service offers a free service that notifies you of incoming mail, helping you detect missing mail sooner.
  • Monitor Your Bank Statements: Regularly check your accounts for unauthorized transactions and report suspicious activity immediately.
  • Verify the Issuing Bank: If you receive a check from an unfamiliar source, call the bank listed on the check using the contact information from their official website.

What to Do If You’re a Victim of Check Fraud

If you suspect check fraud, take immediate action to minimize financial loss:

  • Notify Your Bank: Report the fraudulent activity and request a hold on your account if necessary.
  • File a Police Report: Document the fraud with your local law enforcement agency.
  • Report to Federal Agencies: The FTC, U.S. Postal Inspection Service, and the FBI’s Internet Crime Complaint Center accept reports of financial scams.
  • Monitor Your Credit: Fraudsters who steal checks may also attempt identity theft. Consider using credit monitoring tools to detect future unauthorized activity.

Stay Protected with First Financial

Check fraud can happen to anyone, but awareness and preventative measures can keep your finances secure. By staying vigilant and following these best practices, you can reduce your risk of falling victim to check scams. If you suspect fraud or unusual transactions on any of your First Financial accounts, call us at 732.312.1500 or visit your local branch today.

Winter 2025 Newsletter

We hope you’re enjoying the home stretch of these frigid winter months!

In a continued effort to go green, we’re publishing our quarterly member newsletter electronically – it can also be found on our website and social media sites. Paper copies will be available in our branches.

The Winter First Edition Member Newsletter features the following articles:

To view a copy of the newsletter, click here.

We hope that the first quarter of the new year has been a great one!

How Cash Stuffing Can Change Your Budgeting Journey

Although the financial goals you are saving for and the amounts you “should” have saved to reach them can look different depending on what life stage you are in, one thing is certain — making a plan to save is one thing, and sticking to it is another. Despite the challenges that come with saving, personal finance experts agree that you should have sufficient emergency savings (often referred to as an emergency fund) to cover three to six months’ worth of living expenses in the case of an unforeseen emergency. However, saving for long-term financial goals or life’s unexpected twists and turns is often put on the backburner in the face of monthly, or unexpected bills and expenses. Oftentimes, many feel discouraged to save by not having a clear idea of where their money is spent. There are various budgeting techniques that can help rein in spending and identify room to save – one of which is called Cash Stuffing.

What is Cash Stuffing?

Cash Stuffing, also known as the envelope system – is a budgeting method in which you convert your spending money into cash and stuff it into envelopes earmarked for different categories where you expect to spend during a specific timeframe. You would typically withdraw this cash when you receive your paycheck in an effort to budget where it will be going until your next paycheck. By setting cash aside in envelopes designated for specific purposes, you are encouraged to commit to spending only what you’ve allocated for a particular category.

How Do I Get Started?

1. Determine Your Typical Monthly Spending Categories

The success of cash stuffing lies in your ability to realistically project what you will be spending on. Determining the categories you typically spend money on can be done through brainstorming or going through your bank statements for the previous few months. There is no limit to the types or number of categories you can choose, but some common categories include:

  • Rent and bills
  • Groceries
  • Gas
  • Dining/takeout
  • Entertainment
  • Clothing

If you would like to take your cash stuffing one step further, you can create a category for saving. Unlike your spending categories, your saving category should remain untouched during the timeframe you choose, and can later be put into your savings or retirement accounts.

2. Set Spending Limits for Each Category

Decide how much you would like to spend on each category for the timeframe you choose. It is important to be realistic — for example, you can’t skimp out on paying your fixed expenses, such as rent and bills. Even if you don’t fill up those envelopes, those bills are still due. However, this step offers an opportunity to identify categories where you could potentially rein in your spending. If you notice you don’t typically use all of your groceries, or you impulsively buy coffee out multiple times a week, try setting your spending limit lower for those categories than it has been in previous months.

3. Decide How You Will “Cash Stuff”

While tried-and-true cash stuffing is done by stashing white envelopes in a box, the method has gotten much more creative in recent years. You can decorate the envelopes or color-code labels, or even purchase “budget binders” that can hold all of your cash envelopes.

Cash Stuffing Can Be Done Digitally: Cash stuffing digitally can eliminate worries about having your funds lost or stolen. In this case, you would create a spreadsheet and save it on your computer or tablet, still track your categories and spending limits, as well as how much you have spent and what’s still remaining. If creating a spreadsheet is not your forte, there are also phone apps and websites that can help create and manage digital envelopes to visualize your spending.

4. Withdraw Your Cash and Stuff Your Envelopes

Once you have determined how much money you would like to allocate to each category, add up your spending limits and withdraw that amount in cash. Then as the name suggests, “stuff” the cash into your envelopes.

5. Spend with Your Envelopes

Here is where self-discipline comes into play. Whether the cash contained in the envelopes is meant to last you for two weeks or a month, cash stuffing is designed to work if you only spend what you have set aside in each envelope. When you go to use your debit or credit card, remember that you are going over the budget you set for yourself.

The first time you attempt this budgeting method, you might notice that you have allocated too much or too little to certain categories. That’s okay — don’t go into cash stuffing with the expectation that your budget will be perfect the first time. You can tweak your categories, spending limits, or both – to fit your typical spending habits.

6. Save Any Excess Cash

If you notice that you have a surplus in one of your categories, try to avoid moving it to another category where you may find yourself wanting to spend more. You also don’t want to save it to spend the following month. Having excess cash affords you the opportunity to make extra payments towards debt, or to build up your savings account.

As far as budgeting methods go, cash stuffing is customizable to your financial needs and goals. Whether you are embarking on the cash stuffing journey to control your spending, pay off debt, or build your savings — First Financial is here to help you along the way. Check out our financial calculators that are available on our website, as well as our budgeting guide and fillable PDF worksheet. Stop in and see us in any of our branches if you still have questions, or call us at 732-312-1500 to set-up a financial review appointment.

Common Tax Errors to Avoid

Navigating the U.S. tax system can be challenging. How you will file depends on your income and filing status, as well as which tax deductions and credits you can claim. Your taxes are your responsibility, even if someone assists you in filing them.1 As you prepare your taxes, here are some common filing issues that you may be able to manage with a bit of preparation.

Keep in mind that this article is for informational purposes only. It’s not a replacement for real-life advice, so make sure to consult your tax, legal, and accounting professionals before modifying your strategy. Remember, tax rules are constantly changing, and there is no guarantee that the treatment of certain existing rules will remain the same.

Error 1: Overlooked Side Income

Taxpayers must claim any income they’ve received in a tax year. One area that some taxpayers overlook is claiming side money that is in addition to their normal salaries. If you receive income from efforts outside your regular wages or self-employment, then you are obligated to report what you receive.

This money usually isn’t reported on a 1099 or W-2 and can include income from the following sources (and more): 2

  • Hobbies that yield a profit
  • Bartering for services or property
  • Forgone interest from below-market loans
  • Canceled debt, including discounts on mortgage loans
  • Social Security benefits to spouses and dependents (subject to filing status and income)
  • Unemployment compensation

Error 2: Unrealized Tax Breaks

Tax breaks can help you manage the taxes you owe or change your liability, resulting in greater benefits for you. While deductions are one form of a tax break, others include tax credits, exemptions, and certain tools designed to help you manage your tax burden. 3

Error 3: Wrong Filing Status

Your filing status can greatly impact your taxes because it defines your standard deduction and tax brackets. A common reason people choose an incorrect status is that their status has changed during the tax year. Before filing your taxes, be sure that you’ve updated your tax paperwork to reflect any changes to your filing status.

The five tax filing statuses are:

  • Single: Taxpayers who aren’t married, are divorced, or are legally separated (as state law dictates).
  • Married Filing Jointly: Taxpayers who are married and will file a combined joint return. Widow(er)s can typically file a joint return within the first tax year of losing their spouse.
  • Married Filing Separately: Taxpayers who are married and choose to file separate tax returns, which may or may not decrease their tax liabilities.
  • Head of Household: Taxpayers who are typically single and pay at least half of all home expenses for themselves and a qualified person.
  • Qualifying Widow(er) with a Dependent Child: Taxpayers whose spouse has died within the past two years and who have a dependent child, assuming other qualifications are met.4

Error 4: Incorrectly Claimed Dependents

Taxpayers can claim dependents for whom they are financially responsible during a tax year. The IRS defines a dependent as a “qualifying child” or “qualifying relative.” Taxpayers can no longer claim personal exemptions for each dependent, and they can miss out on other tax benefits by incorrectly claiming or forgetting a dependent. Be aware that if you have a blended family in which you share children with another taxpayer, you could end up accidentally claiming children when only one parent would be able to do so.5,6

Error 5: Not Having Proof of Purchases

Your paperwork is crucial for filing taxes correctly and includes everything from your pay slips to receipts. Beyond helping you file taxes, your documents also serve as proof of the claims you make on your return. Should the IRS find any errors or choose to audit you, you’ll need these records to back up the numbers.

A partial list of items to have on hand for verifying your financial records includes receipts, mileage, documents on life events, and medical and expense records for home improvements.7

Error 6: Not Accounting for Income

Your or your family’s income is the key determinant of how much you’ll pay in federal taxes. The IRS will tax you at a rate depending on the total you report.

In Conclusion

Filing your taxes can be a complex responsibility, and accidental errors can be easy to make. By being diligent, carefully strategizing, and keeping tight records, you can improve your ability to file taxes in a timely fashion while attempting to follow all of the federal and state guidelines. Even if you’re choosing to work with a tax professional, you are responsible for making sure you correctly file your financial details.

Remember, if you have any questions about your financial life, we’re here to help you navigate this complicated landscape. We always welcome collaborating with your tax professionals to align the strategies you take across your financial priorities. You can call or email the financial professionals in the First Financial Investment & Retirement Center at 732-312-1534, mary.laferriere@lpl.com or maureen.mcgreevy@lpl.com

Securities and advisory services are offered through LPL Financial (LPL), a registered investment advisor and broker/dealer (member FINRA/SIPC). Insurance products are offered through LPL or its licensed affiliates. First Financial Federal Credit Union (FFFCU) and First Financial Investment & Retirement Center are not registered as a broker/dealer or investment advisor. Registered representatives of LPL offer products and services using First Financial Investment & Retirement Center, and may also be employees of FFFCU. These products and services are being offered through LPL or its affiliates, which are separate entities from and not affiliates of FFFCU or First Financial Investment & Retirement Center.

Securities and insurance offered through LPL or its affiliates are:

This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results. Consult your financial professional before making any investment decision. Opinions expressed are subject to change without notice and are not intended as investment advice or to predict future performance. All information is believed to be from reliable sources; however, we make no representation as to its completeness or accuracy. Please consult your financial professional for further information. These are the views of FMG Suite, LLC, and not necessarily those of

the named representative, broker/dealer, or investment advisor and should not be construed as investment advice. Neither the named representative nor the named broker/dealer nor the investment advisor gives tax or legal advice.

Sources: 1-7 IRS.gov, 2024